Living in San Diego is incredible… until the bills start piling up.
Rent alone averages over $2,800 a month. Gas is expensive. Groceries keep climbing. And if you’re like a lot of people here, credit cards quietly became the safety net somewhere along the way.
You use one card to cover groceries. Another for utilities. Maybe a third just to smooth things out until the next paycheck. Then the interest kicks in. Right now, the average California household carries more than $13,000 in credit card debt, and most of it sits at interest rates above 20%.
At that point, the math stops working. Minimum payments barely touch the balance. The balance barely touches the interest. And the cycle just keeps going. If that sounds familiar, you’re not alone. Thousands of San Diego residents are stuck in the same loop.
There is a legal exit ramp. It’s called bankruptcy. And despite what people assume, it wasn’t designed as a punishment. It was created specifically to give people a financial reset when debt becomes impossible to manage. For qualifying residents, bankruptcy can:
- Eliminate credit card balances entirely
- Stop collection calls immediately
- Freeze lawsuits and garnishments
- Give you a clean financial slate
So let’s walk through what that actually looks like in San Diego.
Does Bankruptcy Actually Erase Credit Card Debt?
Yes. And here’s why. Credit cards fall into a category called unsecured debt. That simply means the debt isn’t tied to an asset. A mortgage is tied to a house. A car loan is tied to a vehicle.
Credit cards? Nothing is backing them. Because of that, unsecured debt is the primary type of debt that bankruptcy eliminates.
When a bankruptcy court issues a discharge order, your legal obligation to repay those balances disappears. Permanently. Creditors can’t:
- Sell the debt to collectors
- File another lawsuit
- Attempt to collect later
Once discharged, it’s legally gone. For many people, that moment is the first real financial breathing room they’ve had in years.
Why Credit Card Debt Hits So Hard in San Diego
San Diego is one of the most expensive cities in the country. That reality pushes a lot of households into a quiet financial balancing act. You know the moment. Rent jumps $300. Groceries jump another $200. But income… stays the same.
So people bridge the gap with credit cards. Not because they’re reckless, because they’re trying to keep life moving. The problem is what happens next.
Take a $25,000 credit card balance at 22% interest. That balance adds roughly $5,500 in interest every year, even if you never use the card again. That’s not really a debt problem anymore. It’s a compounding math problem. And eventually the numbers stop being survivable.
That’s why California consistently ranks among the states with the highest bankruptcy filings. In 2024 alone, there were over 47,000 cases statewide, and San Diego accounts for a significant portion.
Not because people are irresponsible. Because the cost of living here is relentless.
The Moment Bankruptcy Is Filed, Everything Stops
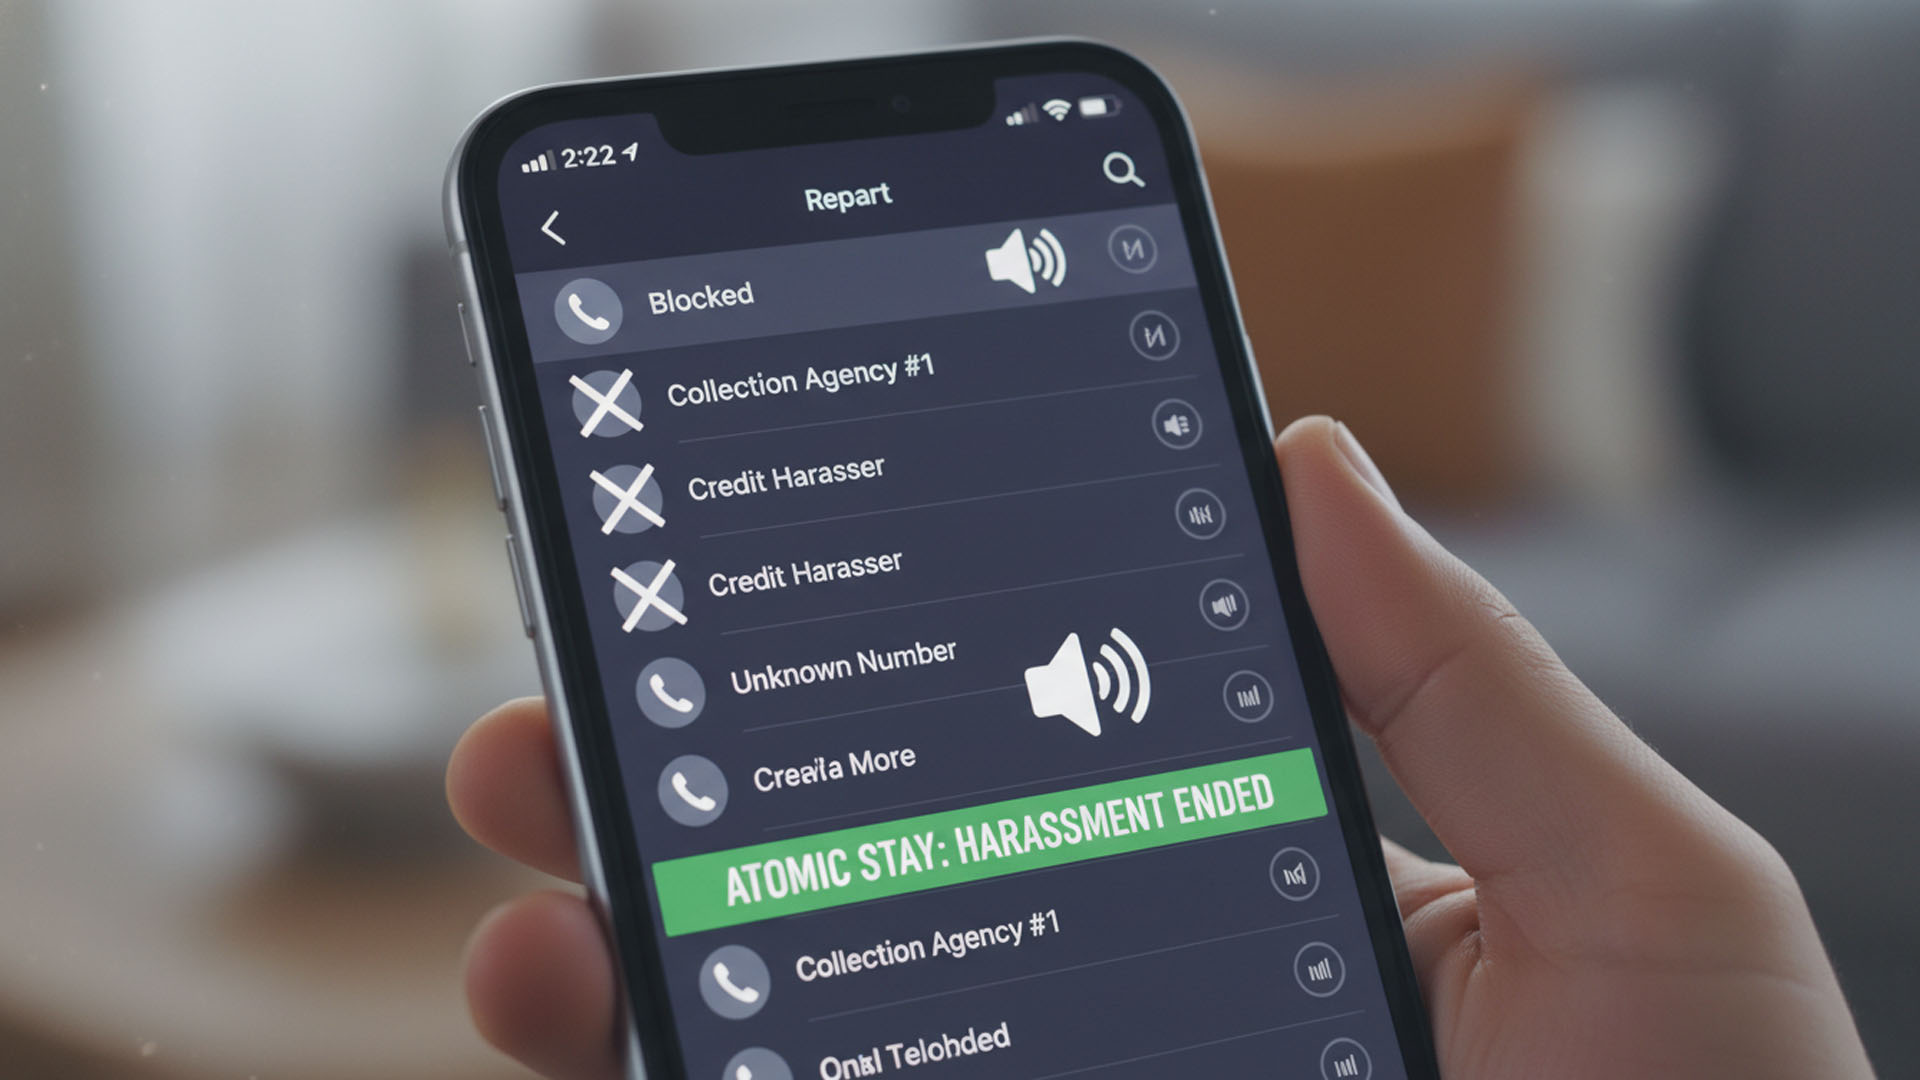
One of the most powerful protections in bankruptcy is something called the automatic stay. It sounds technical, but the idea is simple. The moment a bankruptcy case is filed, the court issues a legal order that forces creditors to stop collection activity immediately. That means:
- Collection calls stop
- Collection letters stop
- Wage garnishments pause
- Lawsuits freeze
- Judgments stop moving forward
If you’ve been dealing with daily calls from collectors or watching your paycheck shrink because of a garnishment, that protection alone can change your life overnight.
People often describe the moment after filing as the first time they’ve slept peacefully in months.
Chapter 7 vs Chapter 13: What’s the Difference In Eliminating Credit Card Debt?
Most personal bankruptcies fall into one of two categories. Chapter 7 and Chapter 13. Both can eliminate credit card debt. They just do it differently.
Chapter 7 Bankruptcy
This is the faster option. For many people with primarily credit card debt and limited assets, Chapter 7 wipes out the entire balance.
This is the faster option. For many people with mostly credit card debt and limited assets, Chapter 7 wipes out the entire balance. It takes about three to four months from filing to discharge in a straightforward case. We break down every stage in the full Chapter 7 and Chapter 13 timeline.
Chapter 13 Bankruptcy
Chapter 13 works differently. Instead of eliminating debt immediately, it creates a 3–5 year court-supervised repayment plan. You pay what you can reasonably afford. At the end of the plan, any remaining unsecured debt is discharged. Chapter 13 is often used by people who:
- Are behind on a mortgage
- Earn too much to qualify for Chapter 7
- Want to protect assets that exceed exemption limits
But for many San Diegans with mostly credit card debt, Chapter 7 tends to be the cleaner and faster option.
Do You Qualify for Chapter 7?
This is where the California means test comes in. It is an income check. To qualify for Chapter 7 automatically, your household income needs to fall below the California median for your household size.
For cases filed on or after 15 July 2026, those medians are:
- One earner: $79,253
- Household of two: $102,797
- Household of three: $116,541
- Household of four: $139,071
Source: U.S. Trustee Program, Census Bureau Median Family Income by Family Size. These figures are updated roughly every six months, so check the current table before relying on them.
Earning more than these figures does not end the conversation. The means test subtracts a long list of allowed living expenses before it reaches a final number, and in a county as expensive as San Diego those deductions are large. Plenty of people above the median still qualify. The calculation takes a few minutes in a consultation.
What Happens to Your House, Car, and Retirement?
This is probably the biggest fear people have about bankruptcy. People imagine losing everything. In reality, that almost never happens.
California actually has some of the most generous asset protections in the country through what’s called exemption laws. These exemptions allow you to keep certain property during bankruptcy.
For example:
Home equity
California’s homestead exemption is set by the median sale price of a single family home in your county for the prior year, within a floor and a ceiling that are adjusted for inflation. For 2025 that band runs from $361,076 to $722,507 under Code of Civil Procedure 704.730.
San Diego County sits toward the upper end of that range, because local home prices are high. Because the figure moves every year, the exact amount that applies to your case is worth confirming before you file rather than assuming.
Vehicle equity
California protects up to $8,625 of equity in a vehicle under Code of Civil Procedure 704.010, current as of 1 April 2025.
Equity means what the car is worth minus what you still owe on it. A financed car often has little or no equity to protect in the first place, which is why most people filing Chapter 7 keep the car and keep making the payment.
Retirement accounts
401(k)s, IRAs, and pensions are fully protected under federal law.
Household items
Furniture, clothing, and everyday goods are also protected up to specific limits. In many Chapter 7 cases, people keep everything they own. Choosing the right exemption system is important though. California offers two different sets of exemptions, and selecting the right one can protect significantly more property. That’s one reason many people prefer working with a local bankruptcy attorney instead of filing on their own.
Situations Where Credit Card Debt Might Not Be Discharged
Bankruptcy eliminates most credit card debt, but there are a few exceptions worth knowing about. These situations don’t apply to most people, but they do exist.
-
Recent large purchases.
Under 11 U.S.C. 523(a)(2)(C), a purchase of luxury goods or services over $900 made within 90 days before filing can be presumed non-dischargeable. The creditor still has to raise it, and the presumption can be rebutted.
-
Recent cash advances
A cash advance over $1,250 taken within 70 days before filing can face the same presumption.
Both figures are current as of 1 April 2025 and adjust every three years.
-
Fraud or misrepresentation
If a creditor can prove someone intentionally misrepresented income on an application or charged purchases with no intention of repayment, a court may exclude those specific charges from discharge.
Normal financial hardship, using credit cards to cover rent or groceries during tough times, is not fraud. Most bankruptcy attorneys review your recent statements before filing to ensure there are no surprises.
Bankruptcy vs Debt Settlement vs Consolidation
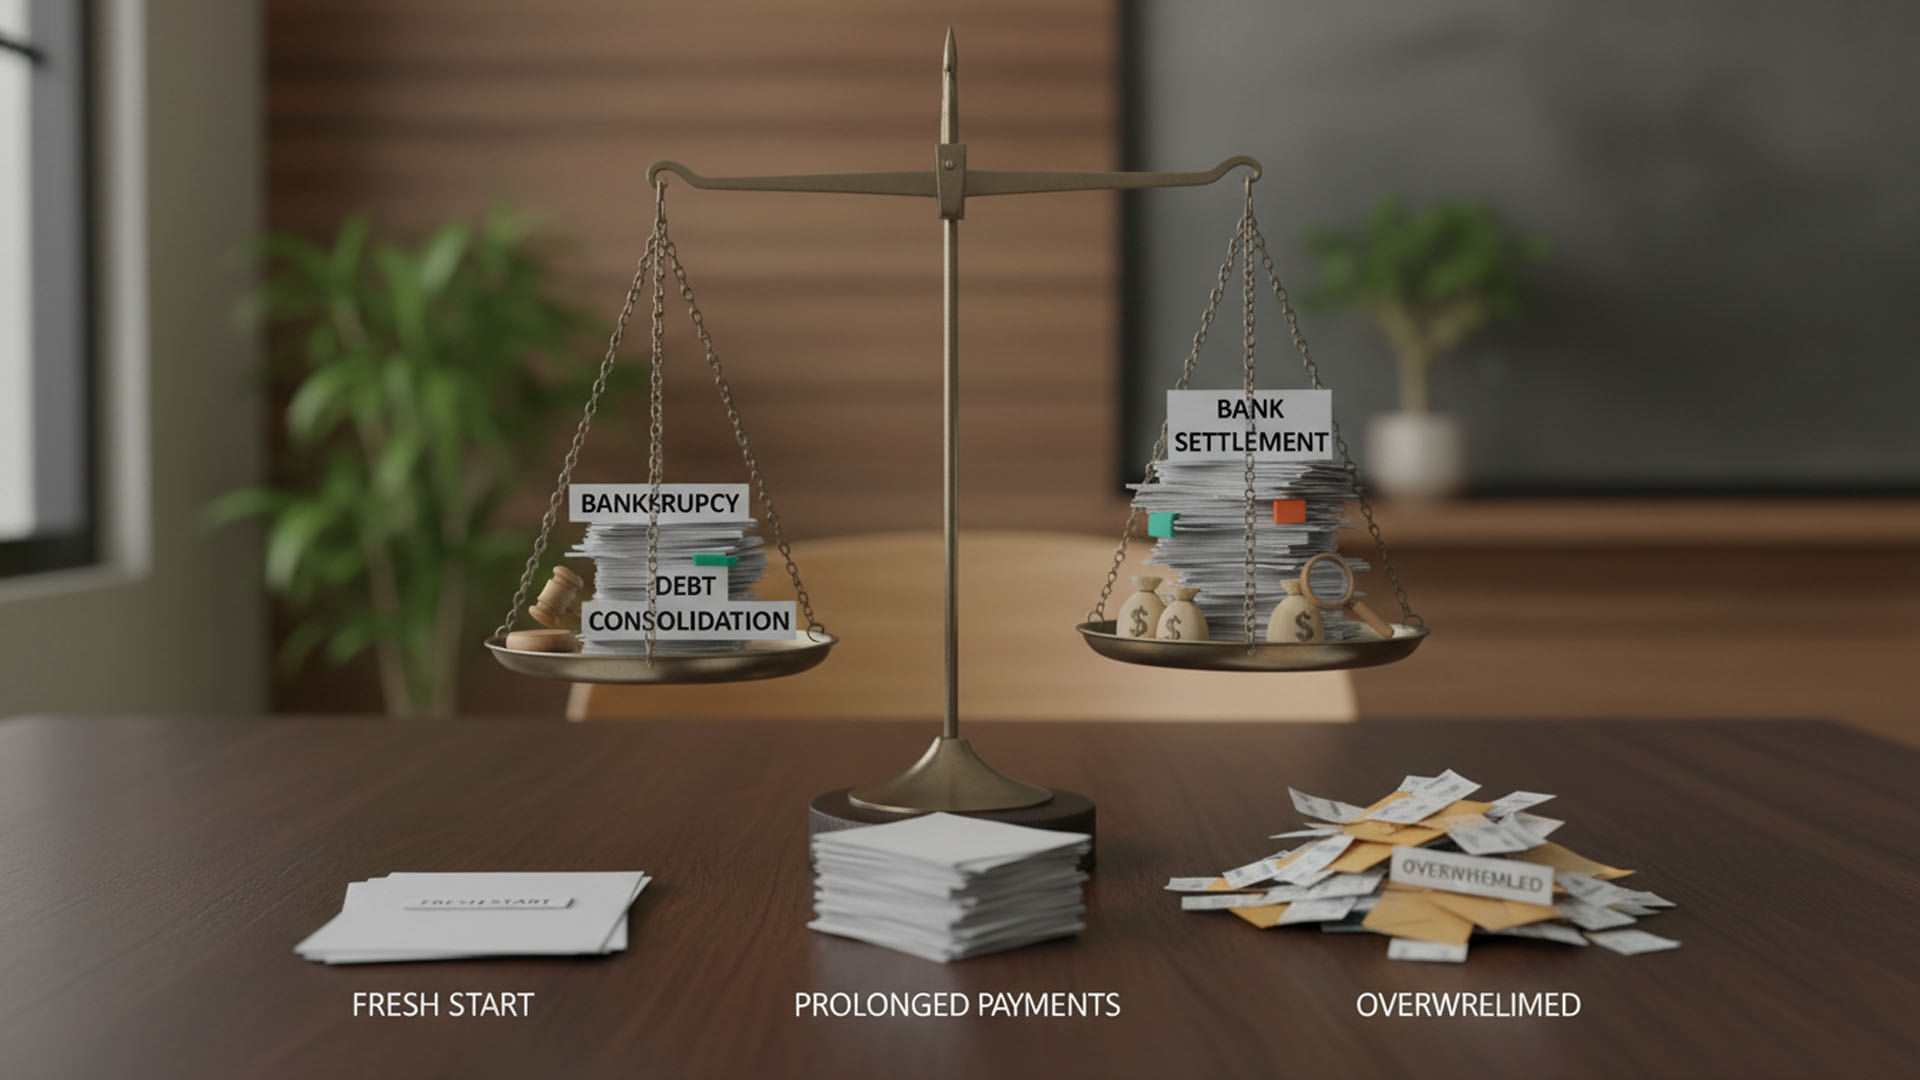
Before considering bankruptcy, many people explore other options. Some work. Some… not so much. Let’s look at how they compare.
Debt consolidation loans
These combine multiple balances into a single payment. The challenge? You usually need good credit to qualify, which many people struggling with debt don’t have. And consolidation doesn’t reduce the balance — it just restructures it.
Debt settlement
Settlement companies negotiate with creditors to reduce balances. The process can take two to four years, and during that time, creditors can still sue. There’s also another catch: forgiven debt can sometimes be taxed as income.
Credit counseling plans
These programs lower interest rates and combine payments. They can work well for people who can realistically repay their balances within three to five years. But if the numbers simply don’t work, these plans can still leave people struggling.
Chapter 7 bankruptcy
Bankruptcy resolves most unsecured debt in three to six months. Collections stop immediately. And discharged debt is not treated as taxable income. For people whose debt would realistically take years to repay, bankruptcy is often the fastest path to financial stability.
What Happens to Your Credit After Bankruptcy?
Bankruptcy does go on your credit report. A Chapter 7 stays for 10 years and a Chapter 13 for 7.
Recovery usually starts well before those dates, because the debt that was dragging the score down is gone. For most people the score is already recovering within the first year.
We cover the full picture, including what changes month by month, in what San Diego filers should really expect from their credit after bankruptcy.
First 6 months
Many people open a secured credit card and use it for a small recurring bill.
6–12 months
Credit-builder loans from local credit unions help rebuild payment history.
1–2 years
Mortgage programs like FHA loans allow applications as early as two years after a Chapter 7 discharge.
3 years and beyond
Many filers reach credit scores in the mid-600s with consistent payment history.
Ironically, some people see their credit improve faster after bankruptcy than before it, simply because the overwhelming debt is gone.
Take The Right Step!
Credit card debt in San Diego isn’t always about discipline. Sometimes it’s just math. When interest grows faster than income, the numbers eventually stop working. Bankruptcy exists to break that cycle.
Chapter 7 can eliminate credit card balances in a matter of months. California exemptions often allow people to keep their home, car, and retirement accounts. And the automatic stay stops collections immediately.
If you’re wondering whether bankruptcy might be the right option, speaking with a qualified San Diego bankruptcy attorney can help you understand your choices.
You don’t have to keep running on the minimum-payment treadmill forever. Sometimes the smartest move is stepping off it.
Common Questions
Does Chapter 7 erase all credit card debt?
It erases most of it. Credit cards are unsecured debt, which is the category bankruptcy is built to eliminate. The exceptions are narrow: purchases over $900 in the 90 days before filing, cash advances over $1,250 in the 70 days before filing, and charges a creditor can prove were made fraudulently.
Will I lose my house or car if I file in San Diego?
Usually not. California protects home equity within a band set by your county’s median home price, up to $8,625 of vehicle equity, and retirement accounts in full. Most Chapter 7 filers in San Diego keep everything they own.
How long does it take to erase credit card debt in Chapter 7?
About three to four months from filing to discharge in a straightforward case. Collection calls stop the day you file, not at the end.
I earn more than the California median. Can I still file Chapter 7?
Often yes. The means test subtracts allowed living expenses before reaching a final figure, and those deductions are significant in San Diego. Income above the median is a reason to run the numbers, not a disqualification.
Is forgiven credit card debt taxed as income after bankruptcy?
No. Debt discharged in bankruptcy is not treated as taxable income. This is a real difference from debt settlement, where forgiven balances can be taxed.