Medical debt alone doesn’t automatically mean you should file bankruptcy, and it doesn’t automatically mean you shouldn’t. There’s no such thing as a separate “medical bankruptcy” category in California; medical bills get treated the same as credit cards and other unsecured debt under Chapter 7 or Chapter 13.
Before filing, most San Diego residents should check whether their hospital owes them financial assistance under California law, since that can wipe out a bill entirely without touching your credit. Filing makes the most sense once medical debt is large, ongoing, or stacked with other unsecured debt.
Before You Consider Bankruptcy, Check These California Options First
It’s often the difference between needing to file and not needing to.
Hospital Financial Assistance Under the Hospital Fair Pricing Act
California’s Hospital Fair Pricing Act requires most nonprofit hospitals, and a lot of the major San Diego hospital systems fall into this category, to offer income-based financial assistance to patients who qualify. Depending on your income relative to the federal poverty level, you may be eligible for a significant discount on your bill, or in some cases the full amount written off.
The income thresholds are usually tied to a multiple of the federal poverty level, and many hospitals extend assistance well beyond what people assume, sometimes covering households making close to 400 percent of the poverty line at a reduced rate. The exact cutoff varies by hospital, so it’s worth asking directly rather than assuming you make too much to qualify.
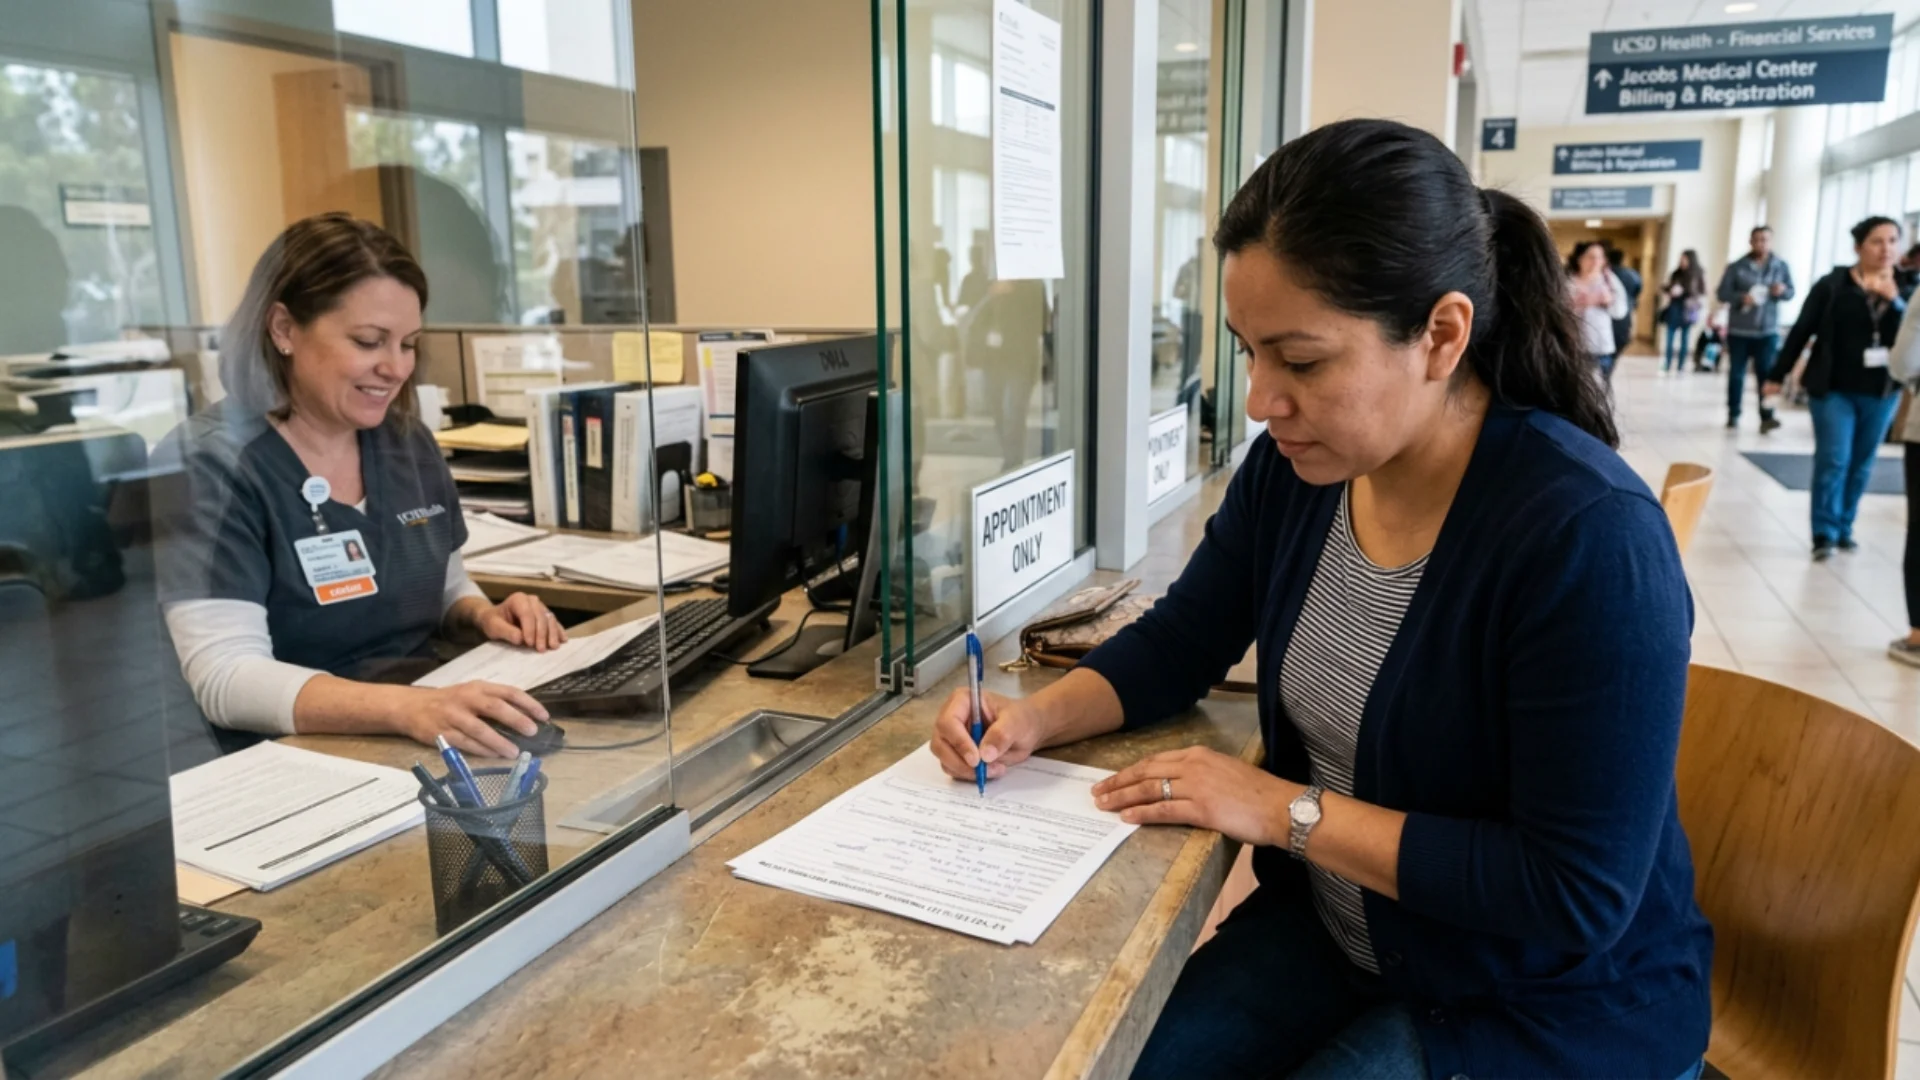
The catch is that hospitals rarely bring this up on their own. You typically have to request a financial assistance application, and there’s usually a window of time after your bill is issued to apply, sometimes up to 240 days. If you haven’t applied for assistance yet and your medical debt is recent, this is worth doing before you spend money on a bankruptcy filing fee, since it might resolve the bill without a filing at all.
Requesting the application usually means calling the hospital’s billing or patient financial services department directly and asking for their financial assistance or charity care application. You’ll typically need to provide recent pay stubs, a tax return, and documentation of household size. It takes some paperwork, but it costs nothing to apply, and it’s worth doing before a bill goes to collections, since some hospitals are less willing to apply assistance retroactively once an account has been sold to a collection agency.
What Changed With Medical Debt and Your Credit Score
The three major credit bureaus changed how they handle medical debt in 2023. Paid medical collections no longer appear on your credit report at all. Unpaid medical debt under $500 doesn’t get reported either. And any medical debt now gets a full year before it can show up on your report, giving you time to work out payment or resolve a billing dispute before it dings your score.
This matters because it changes the calculus. If your medical debt is a single moderate bill and your only real concern is protecting your credit, it may not be showing up on your report the way it would have a few years ago. That doesn’t mean the debt disappears or that collectors stop calling, but it does mean bankruptcy solely to protect your credit score from medical debt is a weaker argument than it used to be.
This protection doesn’t extend to medical expenses charged to a credit card or a medical financing product like a medical credit card. Once a medical bill gets put on a card, it’s treated as ordinary credit card debt for reporting purposes, not medical debt, which means the newer protections around medical collections don’t apply to it. If you’re using a card or financing plan to cover medical costs, that balance behaves like any other credit card balance sitting on your report.
When Medical Debt Actually Crosses Into “Bankruptcy Makes Sense” Territory
Isolated Medical Bills vs. Compounding Debt: the Real Math
A single $6,000 emergency room bill, sitting by itself, with income-based assistance still an option, usually doesn’t justify bankruptcy. The filing fees, the credit impact, and the time involved outweigh the benefit for that kind of isolated debt.
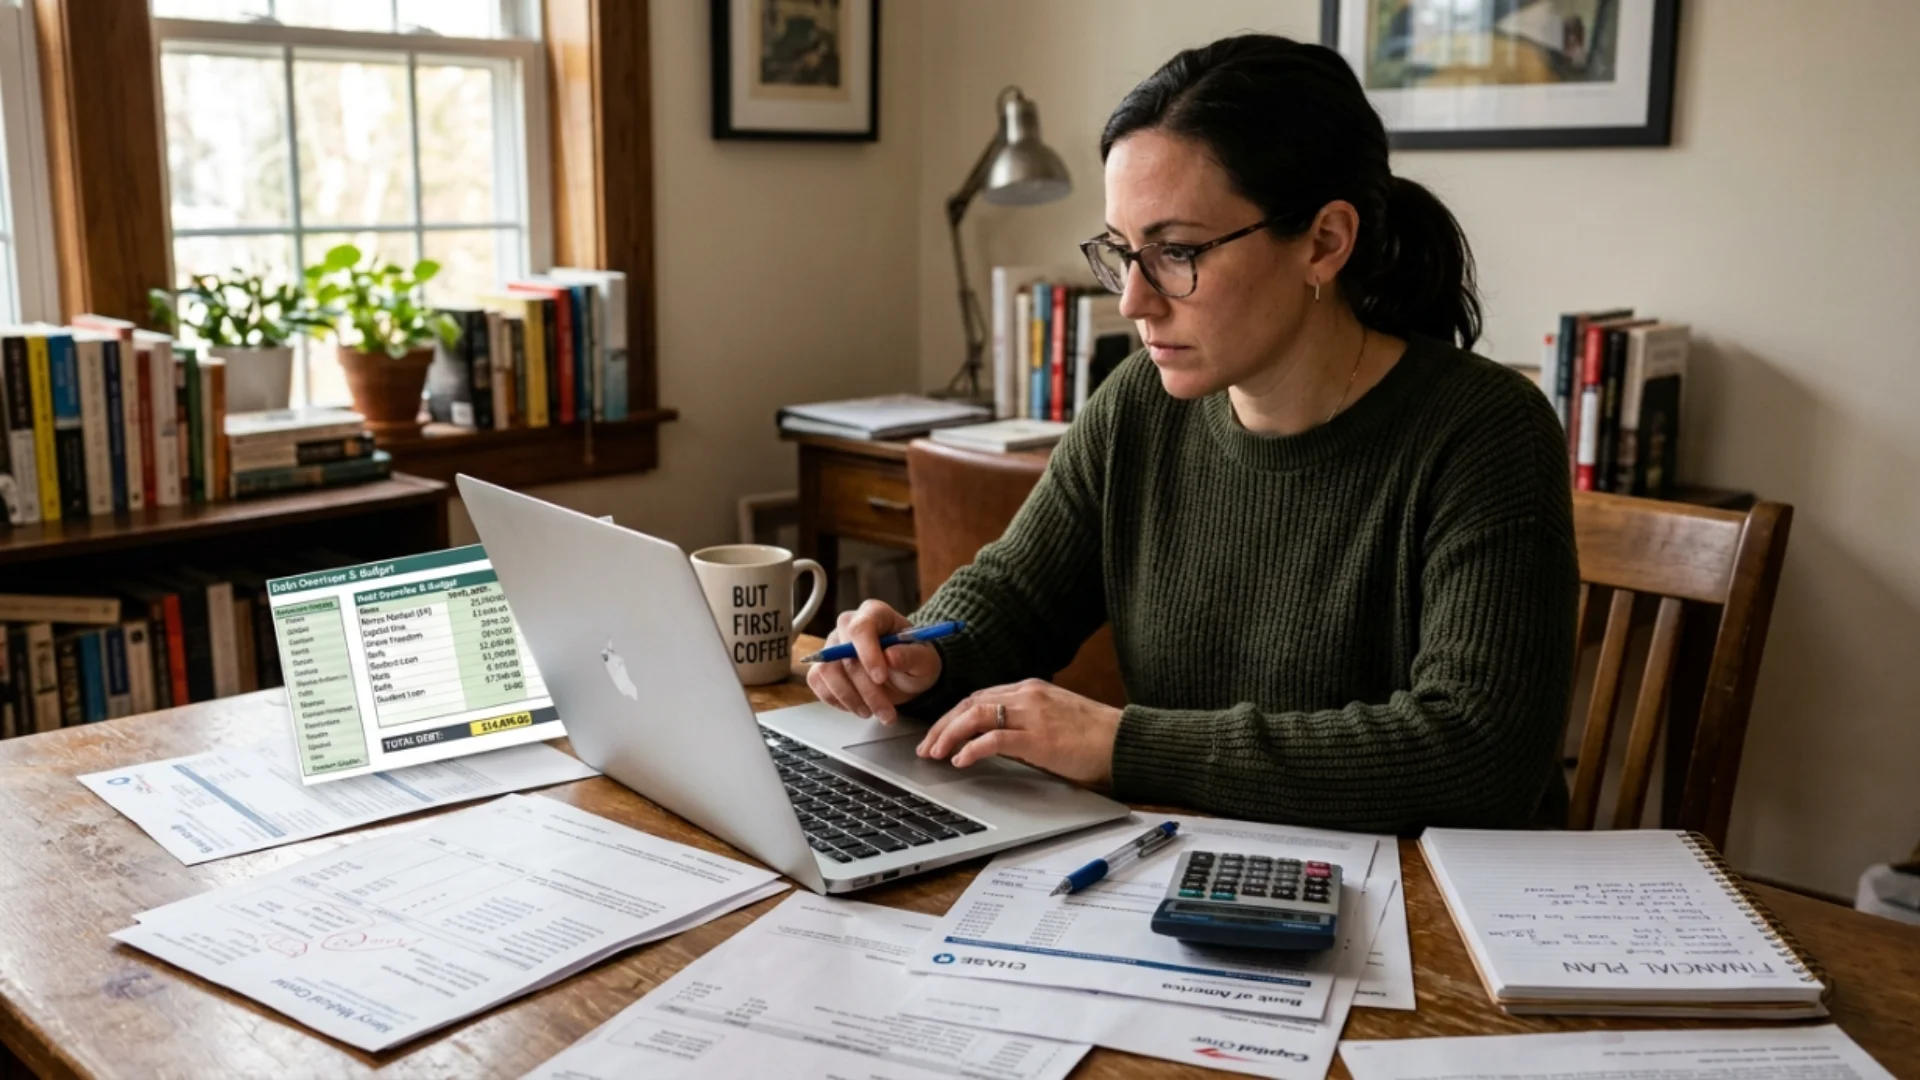
The picture changes when medical debt stacks on top of credit cards, personal loans, or other bills you’re already struggling with. Most experienced San Diego attorneys will tell you the range where filing starts to make financial sense is somewhere around $10,000 to $15,000 in total unsecured debt, medical or otherwise. If your medical bills alone don’t hit that number but combined with everything else you owe you’re well past it, that combination is usually what tips the decision toward filing.
Picture two people with the same $9,000 medical bill. One has no other debt, steady income, and qualifies for a payment plan or partial forgiveness through the hospital. Bankruptcy probably isn’t worth it for that person; the credit hit outweighs a debt they could likely resolve another way. The other person has that same $9,000 medical bill on top of $14,000 in credit card debt from years of falling behind, plus a couple of accounts already in collections. For that person, the medical bill isn’t really the problem on its own, it’s one piece of a much larger debt load that bankruptcy is built to address.
It also matters whether the debt is ongoing. Someone with a one-time surgery bill is in a different position than someone managing a chronic condition who’s going to keep generating new medical bills every few months. If that’s your situation, it’s worth talking through the timing with an attorney, since debt incurred after you file isn’t covered by that filing.
Large, unpaid hospital bills sometimes escalate faster than people expect. Some hospital systems and the collection agencies they sell debt to are willing to sue over medical bills that reach a certain size, and a successful lawsuit can lead to a wage garnishment or a lien against you. If you’ve already been served with a collections lawsuit over a medical bill, that changes the urgency of the decision, since bankruptcy’s automatic stay stops a pending lawsuit and any garnishment tied to it the moment you file.
What Bankruptcy Does and Doesn’t Wipe Out for Medical Debt
When medical debt does justify filing, both Chapter 7 and Chapter 13 treat it as unsecured debt, the same category as credit cards and personal loans. In a Chapter 7 case, qualifying medical debt is typically discharged in full within a few months. In a Chapter 13 case, it gets folded into your repayment plan, and whatever isn’t paid back over the 3 to 5 year plan period gets discharged at the end.
There’s no way to file bankruptcy on only your medical bills while leaving your other debts untouched. Once you file, all your eligible unsecured debt goes into the case together, which is worth knowing if you were hoping to keep some accounts separate.
What bankruptcy generally won’t touch is debt tied to fraud, which is rare in medical billing disputes, and it won’t stop you from owing for medical care you receive after your case is filed. If you’re mid-treatment and expect significant bills ahead, that’s an important factor in deciding when to file, not just whether to.
If you know more medical bills are coming, for an ongoing treatment plan, a scheduled surgery, or a chronic condition that requires regular care, timing matters. Filing too early means new bills after your case closes won’t be covered by that discharge, and you could find yourself facing the same decision again in a year or two.
In some cases it makes sense to wait until a treatment plan is further along, or to combine bankruptcy with a plan for handling the medical costs still ahead. This is exactly the kind of detail that’s worth walking through with an attorney rather than deciding on your own.
Medical debt is one of the most common reasons people end up filing for bankruptcy, but it’s not the only path, and it’s not always the right one. If your bill is recent and moderate, start with your hospital’s financial assistance program before anything else. If your medical debt is compounding with other unsecured debt, or if you’re facing collections and lawsuits with no realistic way to pay it down, bankruptcy stops the pressure and gives you a real reset.
The right move depends on the size of the debt, whether it’s isolated or ongoing, and what else you owe alongside it.
Not sure which category your situation falls into? Filing for Bankruptcy in San Diego starts with a free consultation where a licensed attorney at Bankruptcy Law Offices Of Mark L. Miller can look at your actual numbers and tell you honestly whether filing makes sense, or whether there’s a faster, cheaper path first.